Can You Have Multiple Properties With A Single VA Loan?
You're trying to buy a property and it includes more than one parcel or lot number. Maybe you want the extra acreage behind the house, or there are two structures on adjacent lots. The good news is that a VA loan can cover multiple parcels, but there are rules, practical limits, and plenty of lender interpretation that can make the difference between smooth approval and a denial. This post breaks down what the VA requires, how underwriters actually treat multiple parcels, and what steps you should take to avoid surprises. And if you landed here asking the other version of the question, whether you can own more than one property at a time with a VA loan on each, the answer is also yes, with enough entitlement left and the income to qualify for both payments. That half of the answer starts right below.
Yes. This is the other question people are asking when they land on this page, and the answer
is that nothing in VA's rules limits you to one VA loan at a time. Two things have to be true.
You need enough entitlement left to support the new loan, and you have to qualify for both
house payments under the lender's underwriting.
The new home has to be one you will occupy. VA financing is for a primary residence, so you
cannot use your benefit to buy a pure investment property. What you can do is move, keep the
first house, and rent it out.
VA Handbook Excerpt
“A Veteran with an existing VA-guaranteed loan using $55,000 of their guaranty entitlement is moving to another state and wishes to purchase a new home. The Veteran has opted to retain their existing VA-guaranteed loan; therefore, the entitlement used on that loan cannot be restored.”
That is VA's own example of a veteran holding two VA loans. Keeping the first home is allowed. The consequence is that the entitlement on the first loan stays charged, so the second loan runs on what is left.
How much entitlement is left if you keep the first home
For a loan above $144,000, your available guaranty is 25 percent of the one-unit conforming
loan limit in the county you are buying in, reduced by the entitlement still charged to the loan
you are keeping. Multiply what is left by four and you have the purchase price you can cover
with no down payment.
Run my numbers from Ohio. The 2026 one-unit limit here is $832,750, so full guaranty is
$208,187. If your Certificate of Eligibility shows $88,412 charged to the house you are keeping,
you have $119,775 of guaranty left, which supports about $479,102 with nothing down. Buy above
that and VA expects 25 percent of the overage in cash.
You do not have to do this by hand. Put your county, your entitlement charged and the
purchase price into the
VA bonus entitlement
calculator and it prints the down payment, if any.
Take the 30 second mortgage quiz to see if you qualify
Keep it, rent it, or sell it
Three paths, and the entitlement math is what separates them.
Keep and rent the first home. The entitlement stays charged and you buy
the next home on what is left. Common for PCS moves and for anyone sitting on a low rate they
do not want to give up. How the rent is treated in qualifying, and what documentation the
lender needs, is covered in
keeping your
VA financed home and renting it out.
Sell and pay off the VA loan. Entitlement can be restored once the
property is sold and the loan is paid in full, which puts you back to full entitlement for the
next purchase. Restoration is a request, not an automatic event.
Let someone assume the loan. Careful here. If the buyer is not a veteran
substituting their own entitlement, yours stays tied to that house after the sale. See
selling
a home with an assumable VA loan.
VA Handbook Excerpt
“One-time restoration where the prior VA loan has been paid in full, but the Veteran has not disposed of the property securing the loan. The Veteran may obtain restoration of the entitlement used on the prior loan in order to purchase a different property, one time only.”
There is a one-time exception if you refinanced the first home out of its VA loan but still own it. You can restore that entitlement once. After that, any future restoration requires disposing of every property you bought with a VA loan.
What a foreclosure or short sale does to entitlement
If VA paid a claim on a loan of yours, that amount stays charged against your entitlement
until the loss is repaid. You can still use the benefit again, but on the remaining entitlement
rather than the full amount.
VA Handbook Excerpt
“Entitlement charged on a foreclosed loan cannot be restored until VA's loss on the loan has been fully repaid.”
Two options. Repay VA's loss and get the entitlement back, or buy on what is left and plan for a down payment if the price runs above it. Your Certificate of Eligibility shows the amount charged.
One more thing that trips people up: the underwriting side. Holding two mortgages means the
lender counts both payments unless rental income offsets the first one. VA's handbook sets the
rules for using that rent, but individual lenders add their own reserve and documentation
requirements on top. Those extras are overlays, not VA rules, and they differ from lender to
lender.
What the VA Handbook actually says
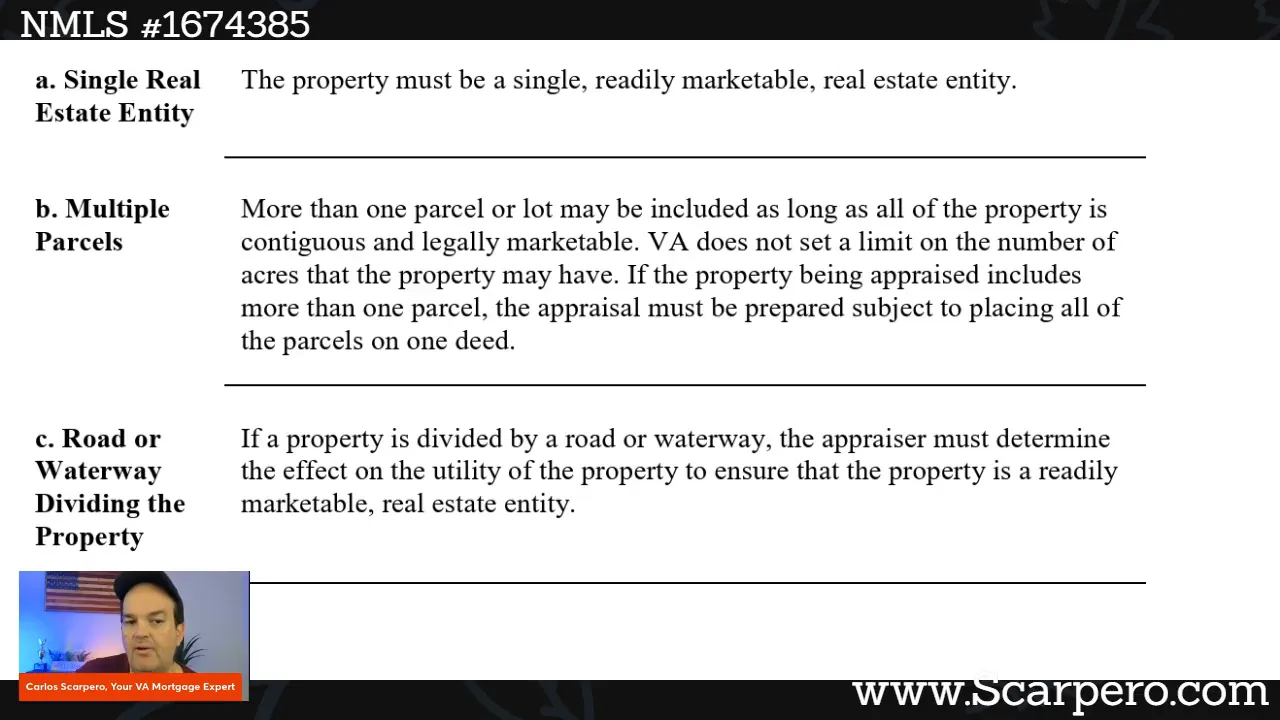
The starting point is the VA Handbook, Chapter 12, Minimum Property Requirements. The core principle to remember is this: the property must be a single, readily marketable real estate entity.
Contiguous parcels are allowed. More than one parcel or lot may be included on a single VA loan as long as the parcels are contiguous and legally marketable.
No VA acreage limit. The VA does not set a maximum number of acres the property may have. Any practical limit usually comes from the lender or appraisal concerns.
One deed requirement for appraisal. If the appraised property includes multiple parcels, the appraisal must be prepared subject to placing all parcels on one deed with the title company.
Roads or waterways do not automatically disqualify parcels. The appraiser must determine whether a road or stream that divides parcels affects the property’s utility and marketability.
How lenders actually underwrite multiple parcels
Although VA guidance is clear in principle, lenders and underwriters often apply additional interpretation. Below are the common scenarios and how they typically play out.
1. Multiple structures on one parcel (straightforward)
If all structures sit on a single lot number, most lenders treat the property as a multiunit property. VA allows up to four units on a single loan. That means a fourplex, two duplexes on the same lot, or a main house with accessory units on the same parcel are usually fine.
You must occupy one of the units as your primary residence, and the other units can be rented. This is one of the clearest “yes” situations you can encounter.
2. House plus a vacant lot (usually fine)
If the seller is including an adjacent vacant lot that is contiguous to the primary lot, lenders commonly allow the parcels to be combined into a single VA loan. Think of it as buying the house and a larger backyard in one transaction.
Two practical requirements here are that the parcels are contiguous and that the title work can place both parcels on the same deed for the loan and appraisal.
3. Multiple houses or separate living units on separate lots (tricky)
When you try to buy two separate houses on two separate lot numbers as a single transaction, lenders often push back. Why? Because that can look like two independent real estate transactions packaged together.
For example, one real-life situation involved a main house on one lot and a neighboring lot with a mobile home. The lender viewed those as two distinct transactions. They requested separate closings: one for the lot and house, one for the lot with the mobile home. If the neighboring mobile home lot were vacant instead, many lenders would accept it, because a vacant lot combined with the primary lot usually reads as one marketable entity.
4. Parcels divided by roads or water (it depends)
The VA handbook explicitly allows parcels divided by a road or waterway if the appraiser determines the division does not impair the property’s utility. In practice, appraisers and underwriters will focus on how the division affects marketability. If the divided layout makes the property awkward to sell, lenders may be reluctant.
Take the 30 second mortgage quiz to see if you qualify
Key documentation and steps to improve your odds
Whether you are the buyer or the agent, being proactive with documentation will save time and reduce the chance of denial.
Title commitment showing all parcels can be placed on one deed. Lenders often require the appraisal to be subject to combining the parcels on a single deed at or before closing. Coordinate early with the title company.
Clear legal descriptions for each parcel. Make sure the sales contract and title work list every lot number and legal description so nothing is missed during underwriting.
Get the appraiser’s buy-in. Ask the lender to assign an appraiser who understands rural properties and multiple-lot situations. The appraiser will be asked to confirm marketability if parcels are divided by a road or stream.
Confirm lender policy on buildability. Some lenders ask whether an extra lot is buildable. The VA handbook does not require the extra lot to be buildable, but lenders sometimes impose that requirement. Ask up front.
Shop lenders or use a broker. Different lenders interpret VA guidance differently. If one lender says no, another may approve the same file. Working with a broker who can present multiple lenders with the same file improves your chances.
Practical tips for veterans and buyers
Start by asking for lender-specific guidance before you write an offer if the property has multiple lot numbers.
Make sure the sales contract includes every lot number and that the seller agrees to place parcels on one deed if required by the lender.
Expect the appraisal to be flagged for multiple-parcel review; the appraiser will assess marketability and any effect of dividing features like roads or waterways.
If a lender declines because of multiple parcels, get a written reason and seek a second opinion, often the issue is interpretation, not VA policy.
Can I use a VA loan for a second home, and can I rent out a VA home later?
These two questions sound alike, but VA treats them very differently. The short version: you cannot use a VA loan to buy a vacation home or a second home you will not live in. You can buy a home with a VA loan, live in it as your primary residence, and rent it out later if you move for a real reason.
Can I use my VA loan for a second home?
No, not if "second home" means a vacation home or a place you visit part of the year. VA financing is for your primary residence. The VA Handbook puts it plainly: use of the property as a seasonal vacation home does not satisfy the occupancy requirement.
What does work is buying the home you will actually live in. If you are moving, whether for a PCS, a job, or family reasons, the new home can be your primary residence even if you already own another house. That is the situation the rest of this page covers: entitlement left, qualifying for both payments, and whether a down payment is needed.
Can I rent out a house I bought with a VA loan?
Yes, after you have lived in it as your primary residence and then move. Buy it, live in it, move for a real reason, and keep it as a rental. That order matters. Buying a house with a VA loan while planning to rent it out from day one does not fit the occupancy certification you sign at closing, which says you intend to occupy the home as your primary residence.
One related case comes up often: you already own a house with a regular mortgage, and you have just become eligible for VA. You can rent out that first house and buy your next primary home with a VA loan, as long as you will live in the new home and you qualify with both house payments counted. The lender will look at how the rent on the first house is treated, so bring the lease and the payment history if you have them. For the full rental picture, see keeping your VA financed home and renting it out.
How soon do I have to move in, and what if I cannot move in right away?
Moving in within 60 days after closing is considered reasonable. If you need longer, you need a specific move-in date and a particular future event that makes that date possible, such as orders, a job start, or a retirement date. Occupancy planned more than 12 months after closing generally cannot be considered reasonable by VA.
A few exceptions cover the situations borrowers ask about most:
Spouse or dependent child moves in. If active duty or distant employment keeps you from occupying the home within a reasonable time, your spouse or dependent child living there can satisfy the requirement.
Deployment. Servicemembers deployed from their permanent duty station are considered to be in a temporary duty status, so they can meet the occupancy requirement with or without a spouse available to occupy the home.
Retirement within 12 months. If you will retire on a specific date within 12 months and buy in your retirement location, that can qualify. Retirement "in the next few years" is not specific enough.
Extensive repairs. If major repairs or improvements keep you from living in the home while the work is done, that is an exception too, as long as you certify you intend to occupy or reoccupy the home when the work is complete.
What helps your file: your orders or retirement paperwork with dates, a clear statement of who will live in the home and when, and a lease or payment history for any home you are keeping and renting. Lenders also add their own documentation rules on top of VA rules, so if one lender says no to an occupancy situation, get the reason in writing and get a second opinion. If your file is complex, start with Complex VA Loans.
If you want me to run your numbers on a second property, take the 30 second mortgage quiz to see if you qualify.
Frequently asked questions
Can a VA loan include multiple lot numbers?
Yes. The VA allows multiple contiguous parcels to be included on a single VA loan as long as the combined property is a single, readily marketable real estate entity. Title and appraisal requirements must be met, including combining parcels on one deed for the appraisal.
Is there a limit on acreage for a VA loan?
The VA handbook does not set an acreage limit. Practical limits come from lender policies, appraisal concerns, and whether the property remains marketable. Some lenders might impose acreage limits under their own guidelines.
What if a road or waterway divides the parcels?
The appraiser must evaluate whether the division affects the utility and marketability of the combined property. If the appraiser determines the divided layout still reads as one marketable entity, the parcels can be included.
Will a lot with a mobile home be allowed?
It depends. If the mobile home is considered a separate, habitable structure on its own lot, a lender may view that as two transactions. If the lot is vacant or the mobile home is demolished, approval is more likely. Lender interpretation varies.
What should I do if my lender says no?
Ask for the specific reason in writing and then get a second lender opinion. Different lenders and underwriters interpret VA rules differently. A broker who shops multiple lenders can often find a program that will accept the parcels.
Can I have two VA loans at the same time?
Yes, as long as you have entitlement left and you qualify for both payments. The second home
has to be one you will occupy. There is no VA rule capping the number of VA loans at two, but
entitlement runs out quickly past that.
Do I have to sell my current home to use my VA loan again?
No. You can keep it and rent it. Selling and paying the loan off is what restores the
entitlement, so keeping the house means the next purchase runs on your remaining entitlement.
Will I need a down payment on the second VA loan?
Only if the purchase price is above four times your remaining guaranty. Check it with the
bonus entitlement
calculator.
Final takeaway
The VA allows multiple contiguous parcels on one loan, but the practical outcome depends on title, appraisal, and lender interpretation. If your deal includes multiple lot numbers, verify early with the lender, coordinate title work so parcels can be combined on one deed, and be prepared to shop lenders if you hit resistance. With the right documentation and the right lender, you can often bundle extra acreage or adjacent vacant lots into a single VA loan, just make sure you plan for the appraisal and title steps up front.