THE SHORT ANSWER
Yes, a mortgage can be declined after the valuation, meaning the appraisal. The two usual reasons are value and condition. If the appraised value comes in below the price, the VA loan amount cannot cover the gap unless the price is renegotiated, the value is reconsidered with comparable sales, or you pay the difference in cash. If the appraiser flags repairs, those have to be resolved before closing. A denial at this stage is usually about the property or the numbers, not about you, and a second look is often worth getting.
By Carlos Scarpero, NMLS #1674385
Last reviewed: November 2026
You found the house, you made the offer, the seller accepted, and then the valuation came back low or loaded with repair conditions. It feels like the deal died. In my experience, it usually has not. It changed. The value and the condition are the two things the appraisal controls, and each one has a real path forward.
I spend a lot of my week on files other lenders have already turned down, and a low valuation is one of the most common reasons a file comes to me.
First, a word on what the valuation is. On a VA loan the appraisal does two jobs at once. It estimates the market value of the home, and it checks the home against VA’s minimum property requirements. The value becomes official in a document called the Notice of Value. The loan amount cannot exceed the lower of the Notice of Value or the purchase price. That is the VA rule that drives everything in this article.
What VA actually requires
VA requires an appraisal on purchase and cash-out loans, and the appraisal has to support the price. If the Notice of Value is lower than the contract price, VA will not guarantee a loan for the full contract price. That is a VA rule, not a lender overlay.
VA also requires the home to meet minimum property requirements: safe, structurally sound, and sanitary. If the appraiser lists repairs, those conditions generally have to be met before closing. Some minor items can be handled after closing only in narrow cases, and your lender has to agree. Do not assume a repair can wait until after you move in.
Reconsideration of value is covered in Chapter 10, Topic 22 of Pamphlet 26-7. After the Notice of Value is issued, you can ask for the value to be reconsidered with additional comparable sales or by pointing out a factual error. That is a real process, not a favor you beg for.
VA HANDBOOK EXCERPT: RECONSIDERATION OF VALUE
“After the NOV has been issued, the Veteran may request reconsideration of value in writing by contacting the RLC of jurisdiction.”
Source: VA Pamphlet 26-7, Chapter 10, Topic 22, Change Date March 11, 2019.
Reason one: the value came in low
A low valuation means the appraiser’s comparable sales do not support the price you agreed to pay. This happens most often in fast-moving markets where buyers bid over asking, or where the home is unusual and good comparable sales are scarce.
You have four options, and more than one can apply at the same time.
Renegotiate the price. Ask the seller to reduce the price to the appraised value. In a market where the seller has other offers, this may fail. In a market where your offer was the only one, it often works.
Ask for a reconsideration of value. If the appraiser missed comparable sales or made a factual error, such as the wrong square footage or a missed bedroom, submit the correct data through your lender. A reconsideration needs real market data, not an argument that the home is worth more because you love it.
Pay the difference in cash. If the gap is small and you have the cash, you can bring the difference to closing. The VA loan covers the appraised value, and your cash covers the rest. Do not drain your reserves to do this. Underwriting still has to see that you can afford the home after closing. Closing costs count too, so read my guide to VA loan closing costs before you count your cash.
Walk away under the VA amendatory clause. Your contract should include the VA amendatory clause, which lets you walk away without losing your earnest money if the value comes in below the price. This is your safety net, and it is one reason VA buyers should never waive that clause. If you need to roll costs into the loan instead, my guide on whether you can roll closing costs into a VA loan covers what can and cannot be rolled in.
Tidewater versus reconsideration of value
These are two different stages, and people mix them up. The table below keeps them straight.
| Stage | When it happens | What it is |
|---|---|---|
| Tidewater | Before the appraisal report is final | The appraiser warns the lender the value looks low, and the lender has two business days to submit additional comparable sales |
| Notice of Value | When the report is issued | The official reasonable value the lender works from |
| Reconsideration of value | After the Notice of Value is issued | A formal request to revisit the completed appraisal with new comparable sales or a factual correction |
Tidewater is the cheapest place to affect the outcome, and it is also the stage that passes fastest. If your agent has comparable sales the appraiser may have missed, get them to the lender during Tidewater, not after. Once the Notice of Value is issued, you are in the reconsideration process, which takes longer and needs more documentation.
My guide on a low VA appraisal, Tidewater, and reconsideration of value walks through both stages in detail.
Appraisal came in low? See what your file can still do.

Reason two: the appraiser flagged repairs
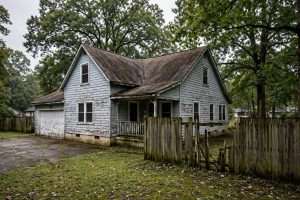
The second reason a file stalls after valuation is condition. The appraiser found something that fails VA’s minimum property requirements: a leaking roof, a broken heating system, peeling paint on an older home, a missing handrail, or water damage. These are not cosmetic complaints. VA wants the home safe, sound, and sanitary.
The usual fix is that the seller makes the repairs before closing, and the appraiser re-inspects to confirm. Who pays is a negotiation, not a VA rule. In a seller’s market the seller may refuse, and then you have to decide whether the home is worth fixing yourself or walking away.
Some repairs can be rolled into a VA renovation loan instead of being fixed before closing. That is a real option when the repairs are large and the seller will not do them. Read my guide on what happens when a VA appraisal fails because of repairs before you decide, because not every repair qualifies for that route.
Your path, step by step
Step 1: Get the appraisal report and the Notice of Value in front of you. Read what the appraiser actually wrote, not what someone told you it says.
Step 2: Separate value from condition. A value problem and a repair problem have different fixes. Work them separately.
Step 3: Gather comparable sales your agent can defend. Recent closed sales, similar size and condition, near the home. Three good ones beat ten weak ones.
Step 4: Ask your lender whether Tidewater is still open or whether you need a reconsideration. Timing decides which door you walk through.
Step 5: Negotiate with the seller from the appraisal, not from emotion. The appraisal is a document. Use it as one.
Step 6: If the numbers cannot work, use the amendatory clause and walk away. Losing a house hurts. Overpaying for one and draining your reserves hurts longer.
A worked example
This is an illustrative example, not a real file. A veteran agrees to pay 310,000 dollars for a home. The appraisal comes back at 295,000 dollars, a gap of 15,000 dollars. The veteran has 8,000 dollars in cash beyond closing costs and reserves, so paying the full gap in cash would leave the file thin.
The agent finds two comparable sales the appraiser missed, both closed within the last 90 days within a half mile, and submits them for a reconsideration of value. The appraiser accepts one, and the value is revised to 302,000 dollars. The gap is now 8,000 dollars. The seller agrees to reduce the price by 4,000 dollars, and the veteran brings 4,000 dollars in cash. The deal closes.
Not every reconsideration succeeds. But a gap of 15,000 dollars is not a dead deal until the comparable sales have been checked. If your value came in low, call me at 937-572-3713 before you give up on the house.
Document checklist
- The full appraisal report and the Notice of Value
- Comparable sales your agent recommends, with addresses, sale dates, and prices
- Photos or records of any feature the appraiser missed, such as a finished basement or a new roof
- Repair estimates if the appraisal lists conditions
- Your purchase contract, so the amendatory clause can be confirmed
What to ask your lender
Ask whether Tidewater is still open, what the reconsideration process needs, and how long it will take. Ask whether the seller can make the repairs or whether a renovation loan fits. And ask what happens to your earnest money if you walk away. If your lender cannot walk you through those answers, get a second opinion. You can reach me at 937-572-3713 or [email protected].
Still want the house? Take the quiz and get a second look.
This question came from veterans asking on Quora. I answer it in full here, and you can see the other questions in What Veterans Are Asking About VA Loans on Reddit and Quora.
Frequently asked questions
Can a mortgage be declined after the appraisal?
Yes. The two usual reasons are a value below the purchase price and repair conditions that fail VA’s minimum property requirements. Both have paths forward: renegotiate, reconsider the value, pay the gap in cash, fix the repairs, or walk away under the amendatory clause.
What is the difference between Tidewater and a reconsideration of value?
Tidewater happens before the appraisal report is final. The appraiser warns the lender the value looks low, and the lender has two business days to submit more comparable sales. A reconsideration of value happens after the Notice of Value is issued, and it is a formal request to revisit the completed appraisal.
Can I pay the difference if the appraisal comes in low?
Yes, if you have the cash and your reserves still look healthy to underwriting. The VA loan covers the appraised value, and your cash covers the gap. Do not drain your reserves to do it.
What if the seller refuses to make the repairs?
You can negotiate a price reduction, pay for the repairs yourself before closing, look at a VA renovation loan, or walk away under the amendatory clause. What you cannot do is close a standard VA purchase loan with unmet repair conditions still open.
Does a low appraisal mean I lose my earnest money?
Not on a VA loan if your contract has the VA amendatory clause, which lets you walk away without penalty when the value comes in below the price. Confirm the clause is in your contract before you rely on it.
Should I order a second appraisal?
A second appraisal is rarely the answer on a VA loan. VA assigns the appraiser, and the lender cannot shop for a better number. A reconsideration with real comparable sales is the proper path. My guide on what to do if your VA loan is denied covers the wider options if the file is denied.
Sources
- VA Home Loans, U.S. Department of Veterans Affairs (benefits.va.gov)
- VA Lenders Handbook (Pamphlet 26-7), Chapter 10, Topic 22, VA KnowVA Knowledge Base
- VA Appraisal Came in Low? Tidewater, ROV, and Your Real Options, Scarpero.com
- VA Appraisal Failed Because of Repairs, Scarpero.com